Profit Is Reported, Cash Is Counted: Free Cash Flow of 385 UK Companies
Does a business turn its profit into cash, and what does it do with it? Asked of every UK-listed company with a track record, on the figures they tag in their own annual reports.
A company can report a profit every year and still run out of money.
Profit is what the accounts say was earned. It rests on judgements: when a sale counts, how fast a machine wears out, what a debt is still worth. Cash is what actually arrived, and it is counted. The two drift apart all the time, and most of the interesting questions about a business live in the gap.
So we asked one plain question of every company listed in the UK that has a track record of digital annual reports: does the business turn its profit into cash, and what does it do with that cash? This post explains the measure, where the figures come from, how the workspace that reads them is built, and what 385 companies turned out to do.

Every company figure in this post is real: read from the companies’ own tagged filings and counted in the workspace on 21 October 2026. The sheet in the first picture (profit 90, cash down to 20) is an invented example. The pictures are stills from a film we made with this post; the case board and detector screens in them are the real workspace, the paper on the black table is ours.
What free cash flow is
The measure for this question is free cash flow.
- Operating cash flow is the cash the business brought in from what it does, after paying staff, suppliers and tax. It is a line of every cash-flow statement.
- Capital expenditure (capex) is what it paid for machines, buildings and software: in IFRS terms, purchases of property, plant and equipment and of intangible assets.
- Free cash flow is what is left: operating cash flow minus capex.
That is the cash a business leaves after keeping and growing its assets. Lenders, dividends and share buybacks are paid out of it. When it is negative year after year, the money comes from somewhere else: savings, new shares or new debt.
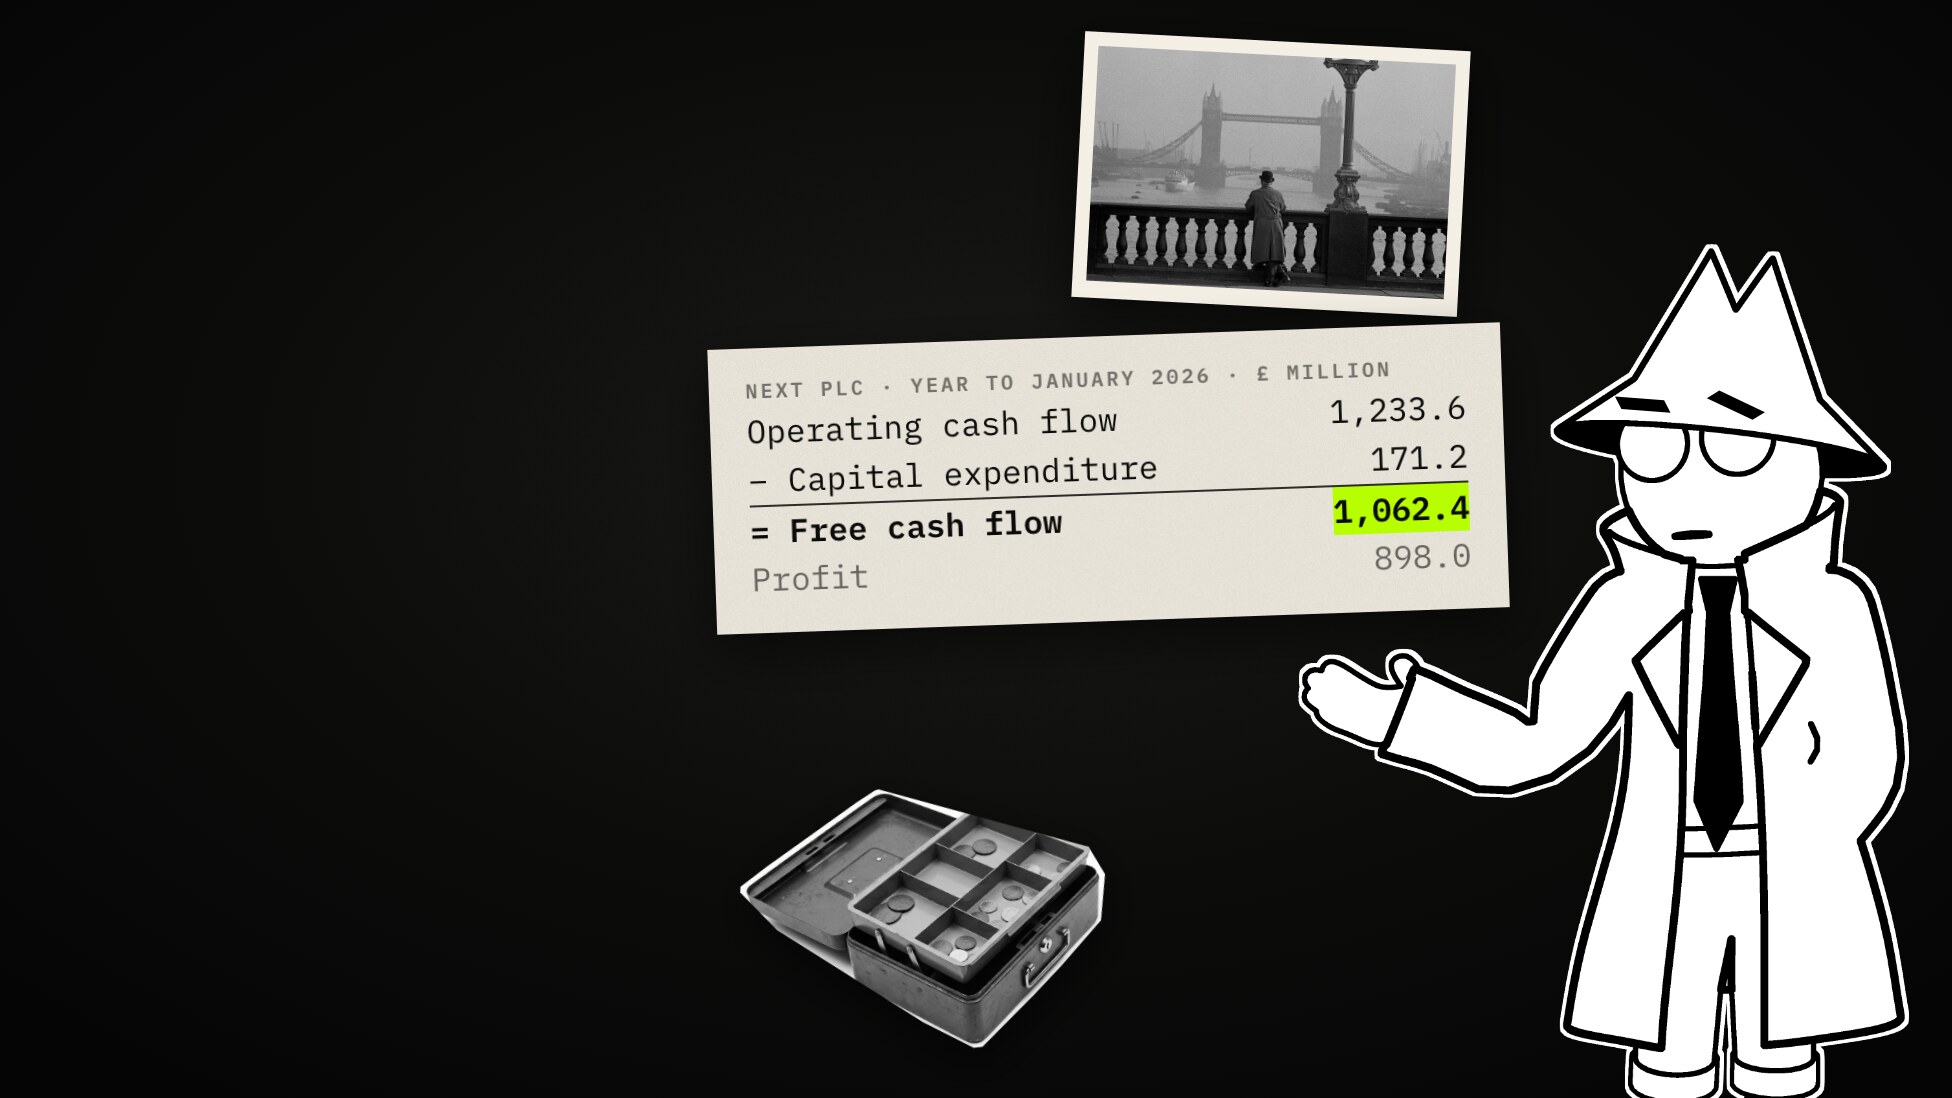
A real year. NEXT plc, the retailer, in the year to 31 January 2026, from its own tagged filing:
| £ million | |
|---|---|
| Operating cash flow | 1,233.6 |
| − Purchases of property, plant and equipment | 135.4 |
| − Purchases of intangible assets | 35.8 |
| = Free cash flow | 1,062.4 |
| Profit for the year | 898.0 |
| Free cash flow as a share of profit | 118 % |
| Dividends paid | 286.5 |
| Share buybacks | 131.4 |
Every pound of profit arrived as cash, and more: depreciation is a cost in the income statement but not a payment. About £420 million went back to shareholders.

One thing to keep in mind from the start: free cash flow is not a line in IFRS accounts. Companies that report it define it themselves, as an alternative performance measure. This workspace uses the plain formula above for every company, so that they can be compared, and keeps what companies call free cash flow as a question of its own (below).
Where the figures come from
For financial years starting on or after 1 January 2021, issuers with
securities on a UK regulated market publish their annual financial report in
the European Single Electronic Format (FCA rule DTR 4.1.14). The report is a
web page (XHTML) in which every figure of the primary statements carries a
tag from the IFRS taxonomy: operating cash flow is
ifrs-full:CashFlowsFromUsedInOperatingActivities in every report, whoever
designed the page.

XBRL International, the not-for-profit body behind the XBRL standard, collects these reports at filings.xbrl.org. For each filing it offers an Inline XBRL viewer, every tagged figure as xBRL-JSON, the report package as filed, and the validator’s messages. In its own words there are, at present, “no restrictions on the ways that the data can be used”, and “the repository is not complete”. Filings arrive from the national collection mechanisms, sometimes well after the original submission.

That is why we read it:
- The figures are the company’s own, tagged by the company, not guessed from a PDF by a scraper.
- The tags line up across companies and across years, so years can be laid side by side without a mapping table per company.
- Anyone can check them against the same page we read, figure by figure.
- It needs no key and no account. The JSON:API at
filings.xbrl.org/api/filingslists 500 filings a request.
Who is in
A company is in when it has at least three reporting periods on the index and a filing submitted this year: a track record, and still current. Then every one of its filings is read, however old, back to 2020 for some.
One surprise on the way: “GB” on the index means filed with the UK regulator, not British. The FCA’s list includes every issuer with securities in London: Kazakh, Russian, Korean, Japanese, Hong Kong and Bermudan groups, the Irish groups, and a British retailer incorporated in Luxembourg. Of the 444 companies that met the rule, 59 name a domicile or country of incorporation outside the UK in their own filings, and they are left out. A first, naive filter also dropped about sixty British companies, because reports converted from PDF print the place as “En gl an d & Wal es”; spaces are now ignored when the place is read.
What remains: 385 British companies, 1,823 filings with periods ending 2020 to 2026, and 12 printed annual reports (2,890 pages) of the largest British non-financial groups, read page by page.

The workspace: three sources and their lineage
In Classifyre this is one workspace with three sources, each a small Python notebook:
| Source | One record per | What it reads |
|---|---|---|
| UK ESEF filings | filing | the index, newest first; each filing’s xBRL-JSON (cash-flow statement, income statement, balance sheet, current and comparative year) and its validation messages |
| UK company profiles | company, and one benchmark per financial year | computed from the filings: a company’s years side by side, converted to pounds at ECB cross rates; a benchmark holds the medians of every company in a year |
| UK annual reports | printed report | the twelve largest British non-financial groups by revenue, cut into pages so that a finding can point at one |
The first source checks the index on a schedule, so a company’s next report joins by itself, and a company that files its first report of a new year joins the workspace.
The connectors also declare lineage: a profile names the filings it was computed from, a benchmark names the profiles behind its medians, a filing names the printed report it was read from. Open NEXT’s profile and its five annual filings and every benchmark it went into are one click away.

The vocabulary: glossary and entities
Records hold figures. A question needs words, and the words live in the glossary: 84 concepts in six groups (free cash flow, IFRS figures, data quality, industries, multi-year trends, kinds of record), each defined in one sentence. A cash machine, for example, is “positive free cash flow two years running, at least 10% of revenue, and at least 80% of profit: the profit arrives as cash.”
Every kind of finding a detector can produce is bound to one of these
concepts. The detector says cash_machine; the glossary knows what that means
and that it sits under strong free cash flow. That binding is what lets a
standing question be asked in words rather than in detector keys.

The companies are in the same glossary, as entities: 385 of them, declared by the profiles source. A small pattern detector finds each company’s Legal Entity Identifier (LEI) in every record, so a company’s filings, its profile and its printed report all land on one entity page.
The readers: rules, a decision model, a language model
Ten detectors read the records. Most are plain Python rules that anyone can read: does the cash-flow statement add up, what is the free cash flow, what do three to six years show together, where does a company stand in its industry. Subtracting two numbers needs no model.
Two questions do, and only there does the workspace use one.
A decision model for the industry
A free cash flow margin means little without peers: a software company and a water company should not be held to the same number. No ESEF tag says what industry a company is in. What every company does give, in its filing, is a description of its principal activities in its own words.
So a decision model reads that text and picks one of eleven industries,
and also answers whether the company is a financial institution. A decision
model is not a chatbot: it gets the question and the options, each with a
description, and returns a probability for every option, no text. Here it is
Perplexity’s Decider (pplx-decider-v1.2) through OpenRouter. (We wrote about
what decision models are
separately.)
For Rio Tinto, whose filing says its business is “finding, mining, and processing mineral resources”, the answer was materials at 99.6%. A Python rule then places each company’s free cash flow margin within its industry: top quarter, bottom quarter, or capex far above the industry’s.

A language model for what companies call free cash flow
What a company means by free cash flow lives in the text of its report, not
in its tags, and the printed reports run to as many as 396 pages (BP’s). A
language model, GLM 5.3 Flash, reads only the pages that use the term:
a pattern on the detector (content_pattern) decides which, in eighteen
languages. That came to about one page in twenty (142 of 2,890).
On each page it writes down the figure, the page, the words used and the definition, and whether leases, interest and acquisitions are deducted. Unilever, page 46: “cash flow from operating activities, less income taxes paid, net capital expenditure and net interest payments.” A Python rule then sets the stated figure against operating cash flow minus capex from the same report’s tags.

Questions that stay asked
Findings are answers. An investigation needs questions that stay asked: the workspace holds thirty of them as inquiry watches, each asked through glossary concepts. Which companies are cash machines? Who leads its industry on free cash flow? Whose cash-flow statement does not add up?
Eight cases are built on them, each one question, each with a desk:
| Case | Asks |
|---|---|
| Cash machines | Who turns profit into cash, year after year? |
| Compounders | Who grew capital and cash in every year? |
| Paying out what they did not earn | Who returned more than it generated, and borrowed the difference? |
| Growth that costs cash | Whose growth eats cash; who is in an investment cycle? |
| Profit without cash | Whose earnings never arrive as money? |
| Numbers that don’t add up | How reliable are UK digital annual reports? |
| What companies call free cash flow | How far is a company’s own figure from the formula? |
| Can search find the number? | Do tagged reports make a ground truth for search? |
A case pulls new answers in as scans land them, and lets a company go when its next report no longer supports the finding. Each case also states two or three hypotheses, claims that sound right, written down before they were tested. The workspace counts each one on the data, writes the tally into a dated note on the hypothesis, links a few findings for and against, and marks it. Of 23 hypotheses, 12 came out supported, 9 refuted and 2 inconclusive. The refuted ones are the most interesting.

What 385 companies did with their cash
All figures are the hypotheses’ tallies of 21 October 2026, on non-financial companies.
Half are steady. Of 231 companies with four or more years, 117 (51%) never had a year of negative free cash flow. (Most UK companies generate cash every year: supported.)
Profit compounds more often than cash, but not by much. Of 232 companies with three or more years, 61 grew profit at least 10% a year; 44 grew free cash flow that fast with every year positive. The cliché says “far more often”. (Refuted.)
Real compounders are rare, and pay their own way. Twelve companies grew their equity by 10% or more in every year, Greggs, NEXT and Halma among them; eleven of the twelve did it without borrowing or paying out more than they generated. (Compounders grow on their own cash, not on debt: supported.)

Cash machines keep most of what they make. Of 69 cash machines that paid dividends, the median paid out 35% of its free cash flow. (Supported.)
Paying out more than the business generates, while debt rises, is the exception. Of 169 companies that paid dividends in three or more years, 18 (11%) paid out more in dividends and buybacks than they generated over the period while net debt rose. (One UK dividend payer in ten borrows to pay out: supported.) And the usual suspect is wrong: where payouts exceed cash, dividends, not buybacks, are the larger part for 18 of 21. (Buybacks, not dividends, open the gap: refuted.) In a single year it is more common: 32 of 213 dividend payers paid more than that year’s free cash flow (15%).

Fast growth that burns cash is not an investment phase. Eight companies grew revenue 10% or more a year while burning cash over the period; none of them had raised its capex share, and five of the eight raised their net debt by half or more. (Investment-led: refuted. Paid for with debt: supported.)
IFRS 16 hides less than people think. Since 2019 most rent is financing cash flow, outside the usual formula. Of 191 companies with positive free cash flow that tag lease payments, only 8 (4%) turn negative once those payments are deducted. (IFRS 16 hides cash burn: refuted.)
Where interest is shown matters. IAS 7 lets a company show interest paid under operating or under financing cash flow. 102 of 385 show it under financing; for 50 it is worth at least a tenth of free cash flow, and 8 cash machines would fall below the 10% margin if they showed it the way their peers do.
Asset-light industries keep more of their revenue. The median free cash flow margin of technology, health care and consumer staples companies is 11.5%, against 7.7% for utilities, energy, materials and telecoms. (Supported.)
The largest free cash flow in the latest year: Shell (£16.65bn), BP (£8.55bn), AstraZeneca (£6.58bn), Vodafone (£6.03bn), Unilever (£5.79bn).
What companies call free cash flow
Ten of the twelve printed reports state a free cash flow of their own. Two things stand out.
- It is usually stricter than the formula. For 8 of the 10, the company’s own figure is lower than operating cash flow minus capex on the same report’s tags: UK companies also deduct interest, tax, leases or investments. For BP and Rio Tinto it is higher. (Companies’ own free cash flow is usually higher than the formula: refuted.)
- It comes with an adjective. Six of the ten qualify the name: BP’s adjusted and modified free cash flow, Compass’s underlying, Sainsbury’s retail, M&S’s free cash flow from operations, Vodafone’s adjusted. The name already tells you it is their own measure.
So two companies’ “free cash flow” are rarely the same number, which is the reason this workspace computes one formula for everyone and keeps the companies’ own figures beside it, with their definitions.
How reliable are the digital reports?
The tags are the company’s own, which cuts both ways.
- Four in five annual reports of non-financial companies tag operating cash flow and capex with standard IFRS elements (1,219 of 1,520); for 57 more, free cash flow can be read only through the company’s own capex element.
- 7% of filings (131 of 1,823) have tagged figures that contradict each other: a cash-flow statement that does not add up, one figure with two values, statements that disagree, a payment with its sign reversed, a filing indexed for one year that holds another. The share is flat, not falling: 4%, 9%, 8%, 6%, 8% for 2021 to 2025.
- Tagging capex with a company’s own element is a habit, not a teething
problem: 13% of filings in 2021, 16 to 17% every year since 2023. A screen
that reads only standard tags misses that investment and overstates free
cash flow. Diageo tags capex as
PurchaseOfPropertyPlantAndEquipmentAndComputerSoftware; RELX, Unilever, Diageo and Tesco tag their buybacks with elements of their own. Without reading those, the payouts case would miss most of the FTSE’s buybacks.
Can search find the number?
Every tagged figure is a verified answer printed on a known page, which makes
the twelve printed reports a free test of document search. We asked the
workspace’s search 201 questions written from the tags
(text-embedding-3-small, 2,890 pages):
| Question | Right report first | Passage on the page that prints the figure |
|---|---|---|
| In plain words (“BP’s operating cash flow for 2025”) | 97–100% | 23% |
| In the statement’s own words | 91–100% | 29% |
| The figure alone (“which page shows 24,483?”), meaning only | 10% | 1.6% |
| The figure alone, hybrid search (meaning and words) | 24% | 48% |
Search by meaning finds the right report nearly every time (the company’s name does the work) but prefers the note that discusses a figure to the statement that prints it. And embeddings do not read digits: a figure alone found its page 1.6% of the time until hybrid search learned to match the words of passages, figures included.
What it does not tell you
- Free cash flow here is the textbook formula. A company’s own measure may suit that company better.
- Banks, insurers, investment trusts, property companies and parent-only accounts are not judged, by their tags, their investment property share or the industry the model reads.
- The industry is a model’s reading, and a model can be wrong.
- Capex from a company’s own element is matched by name; the anchoring ESEF requires is not in the xBRL-JSON.
- “Three years” means three reporting periods on the index, where UK filings go back only to 2020/21.
- A group and its filing subsidiary can both be in (Rolls-Royce Holdings and Rolls-Royce plc, BT Group and British Telecommunications). The medians barely move.
- Amounts are in the company’s currency, with pounds at ECB rates beside them.
And above all: a finding is a question to ask about a company, not a verdict on it.

Open it yourself
The workspace is open to read on the Classifyre showcase, and keeps itself current as new reports are filed:
- Open the case Cash machines and click a hypothesis: its evidence lights up, and its dated note says how it was counted.
- Open NEXT PLC under Entities and follow its lineage to the filings.
- Open the detector Industry from the company’s own words and read the eleven options the model chooses from.
Sources
- XBRL International, filings.xbrl.org and its about page, read on 21 October 2026.
- Financial Reporting Council, UK Structured Reporting Resources (DTR 4.1.14).
- Herbert Smith Freehills, Delay to implementation of European Single Electronic Format for annual reports, November 2020 (FCA PS20/14).
- ESMA, Guidelines on Alternative Performance Measures (2015).
- IAS 7 Statement of Cash Flows and IFRS 16 Leases.
More case files
One Bad Friday at a Pump Factory: Four Rescue Ideas, and the One the Evidence Left Standing
A delivery slips by two weeks and three orders hang on it. Four rescue ideas go on a case board as hypotheses, and one survives. A case file on Nova Manufacturing: an invented pump maker on a real workspace.
Why Germany's Official Numbers Keep Telling the Wrong Story
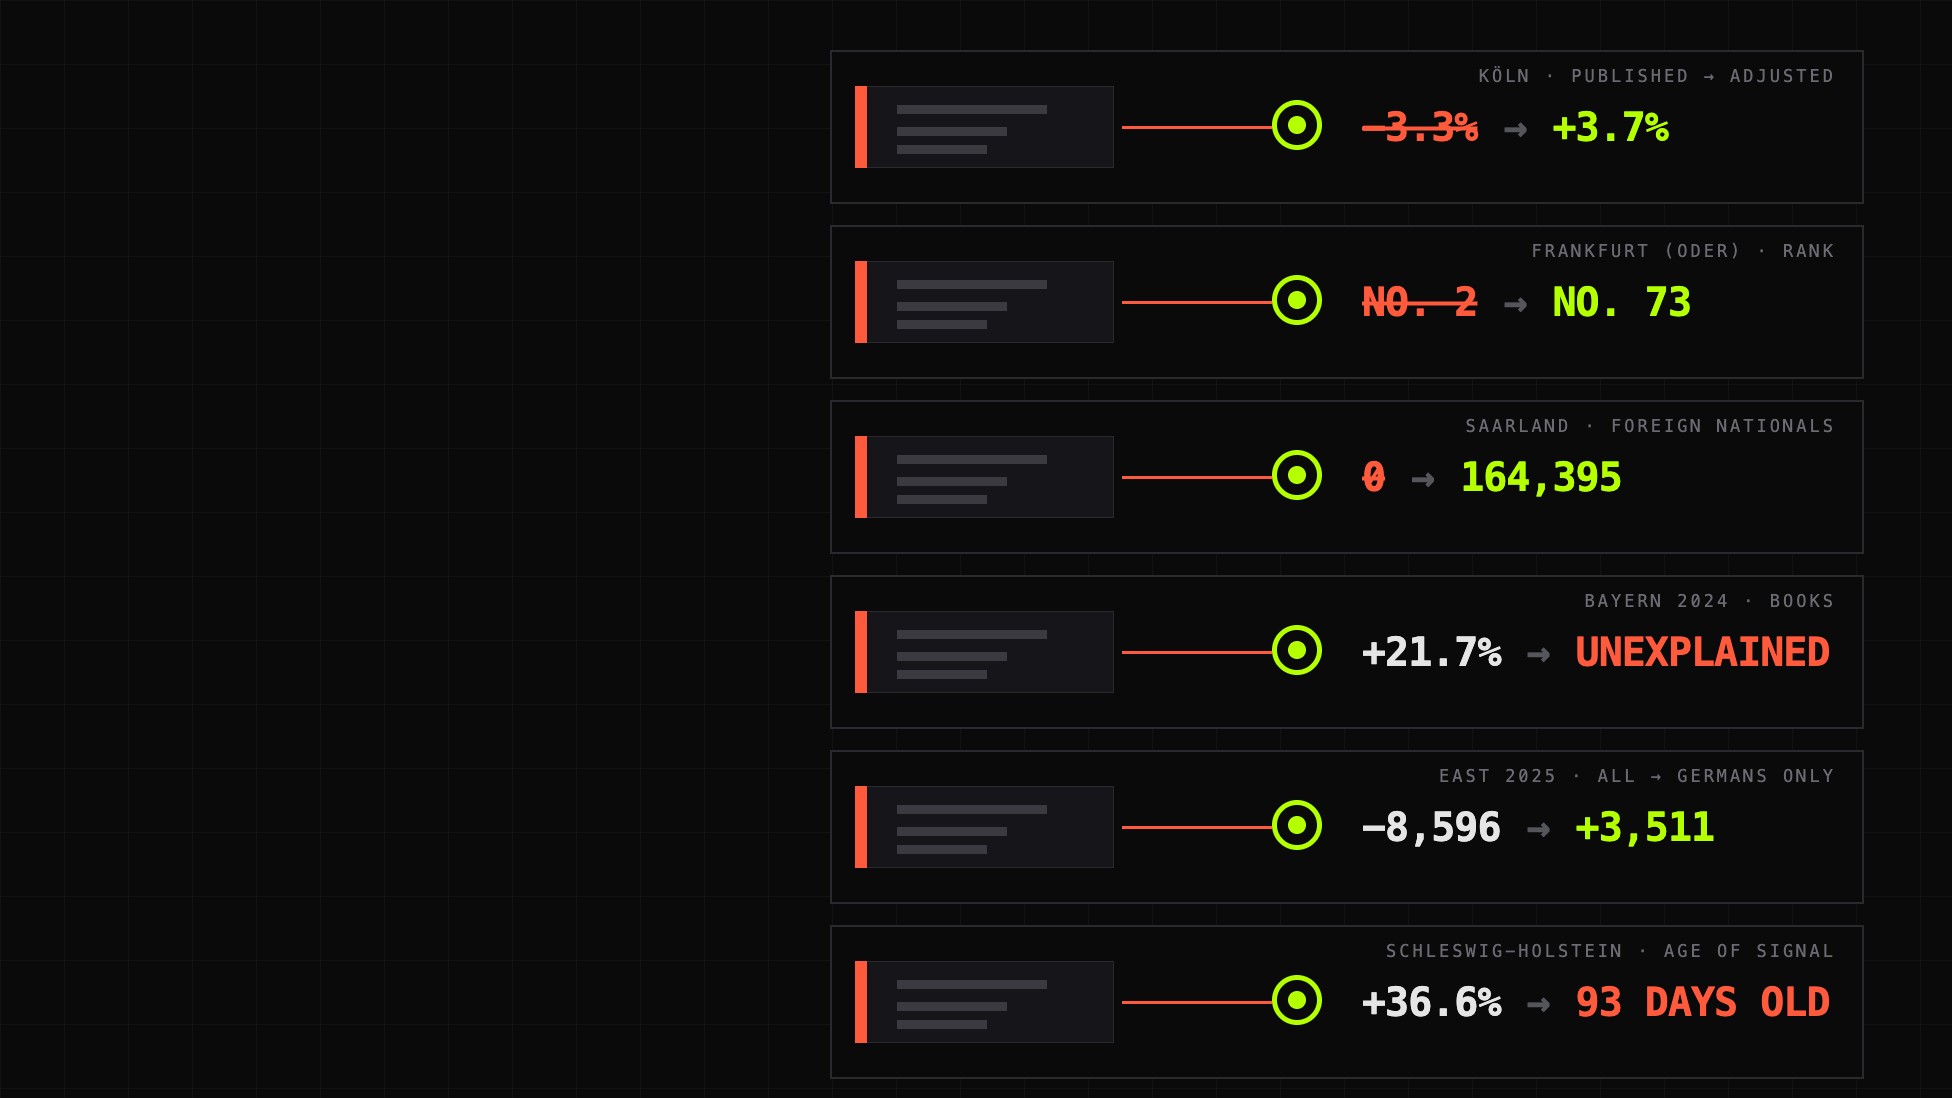
Every figure is correct, and the story is still wrong. We pulled real data from Destatis, the BKA and the EU into one system and went looking for the places where a true number says something false. We found six.